warning signs · GB · GBP
Signs of a casino that does not pay
 Partner campaigns: United KingdomUpdated 18 November 2026
Advertisement · 18+. Bonus, rating and review figures come from the campaign; they are not independently verified reviews. Check eligibility, availability and current terms. Listing does not establish local licensing.
Non-payment rarely announces itself. It shows up as a sequence of small procedural events, each individually defensible, which together keep a balance out of reach. The sequence repeats often enough to be recognisable.
18+ · Great Britain · Editorial guide. PayProof UK is an independent explanatory publication. It does not operate a casino, test personal deposits, rank operators or promise payment times.
The shape of a non-payment case
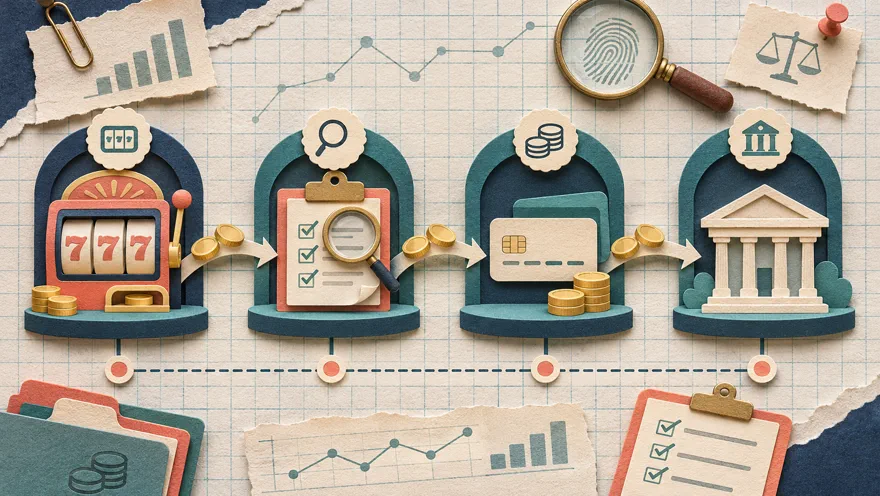
In a dispute that ends badly, the money is usually not stolen. It is held, and the holding is justified by a chain of requests and clauses. A document is requested. The document is sent. A second document is requested, then a clarification of the first. A clause is cited. A review is said to be ongoing. Each step has a plausible explanation; the pattern does not.
That is why individual events are weak evidence and sequences are strong. Any licensed operator can ask for identity evidence, and most will at some point. The signal is a request that arrives only after a win, demands that grow rather than close, and timescales that are restated rather than met.
It is also why dates matter more than feelings. A log of what was asked, when, what was supplied and when converts a frustrating experience into a complaint that an alternative dispute resolution provider can assess. Without dates, a strong case reads as a grievance.
The behaviours below are drawn from the structure of how payouts are refused rather than from any particular operator. Treat them as a checklist against the account you are using now, not as a description of an industry.
Verification that begins at the first large withdrawal
Licensed operators in Great Britain must verify age and identity, and they are expected to do so before allowing gambling rather than at the point of a payout. Verification requested for the first time when a substantial withdrawal is requested is therefore worth noticing, because the obligation did not appear at that moment.
The pattern to watch is not the request itself but its sequencing. Documents demanded only now, documents demanded again after being accepted, demands that escalate from identity to address to source of funds across weeks, and each stage starting its own fresh review period.
A reasonable process names what is outstanding. Ask in writing for a list of the specific items still required and the specific reason the payout is held. A reply that lists two items is a process; a reply that says the account is under review with no items named is a holding pattern.
Keep the uploads and the confirmations. Operators lose attachments, and a document you cannot prove you sent is a document you will be asked for again. Note file names, dates and the channel you used.
| Behaviour | Benign explanation | Why a pattern is different |
|---|---|---|
| First document request at a large withdrawal | Risk-based review triggered by amount | The identity obligation existed before the win |
| Same document requested twice | Upload failed or was unreadable | Repeated without any stated defect |
| Review period restarted at each stage | New information requires new checks | Each restart resets the clock indefinitely |
| Clause cited after the fact | A term genuinely applies | Clause not in the version you accepted |
| One method fails for withdrawals only | Method is deposit-only by design | Stated as available and then silently unavailable |
| Support stops replying | Backlog | Final response deadline passes with no answer |
Goalposts that move
The second recurring behaviour is a requirement that changes shape. A withdrawal is held pending a bank statement; the statement is supplied; now a utility bill is needed; then the bank statement must be a different period; then the name on the statement must match a format nobody mentioned.
Each step is individually arguable. The test is whether the list ever shortens. In a functioning process, satisfying a requirement removes it. In a holding pattern, satisfying a requirement produces a new one, and the total distance to the payout stays constant.
Document this with a simple table of your own: item requested, date requested, date supplied, response. Three rows of that table are usually enough for a reader to see whether requirements are closing or multiplying.
The same applies to timescales. Note each time a period is quoted and each time it elapses. A quoted period that is never met and never explained is a measurable fact, not an impression.
Payment methods that work one way
A less visible sign is asymmetry between deposits and withdrawals. Some methods are genuinely deposit-only, and that is a legitimate design constraint rather than a trick. The problem arises when a method is presented as available for withdrawals and then is not, or when the only method that works for payouts is the slowest one available.
Payment-method matching rules make this sharper. If the terms require withdrawals to return to the deposit source, and the deposit source cannot receive funds, the customer is caught between two provisions. A well-run cashier states this before the deposit; a poorly run one discovers it at the payout.
Check the cashier for both directions before depositing, and prefer a method you have seen stated as valid for withdrawals. Save the cashier page. If a method later disappears from the withdrawal list, your screenshot establishes what you were offered.
Watch also for deductions that appear only at payout. Fees, currency conversion and minimum withdrawal thresholds that are absent from the cashier and present in the terms are a documentation failure even where the charge itself is permitted.
- A method listed for withdrawals that cannot actually be selected when you try.
- Payment-method matching combined with a deposit method that cannot receive payouts.
- A minimum withdrawal threshold higher than the balance the account can hold.
- Fees or conversion charges disclosed nowhere in the cashier.
- Repeated failed payouts with no reason code supplied.
Clauses applied retroactively
The third pattern is a term that appears after the event. A bonus is voided under a rule that was not in the version you saved. An irregular-play clause is cited without a definition. A maximum stake is enforced at a level the cashier allowed you to exceed. A cap is applied that the offer page did not mention.
This is where the dated copy of the terms stops being bureaucracy and becomes the case. If the operator quotes a clause, compare it word for word with your saved version. Where the wording differs, you have a documentary conflict that is simple to state and hard to dismiss.
Where the wording matches, the question becomes whether the clause was presented clearly when you opted in. That is a weaker argument but still a real one, and it is the kind of question alternative dispute resolution is designed to weigh.
Either way, the useful move is the same: quote the clause, quote your saved version, state the date of each, and ask for the specific basis of the decision in writing.
Support that degrades under pressure
Operators are permitted to be slow. They are not permitted to have no complaints process. Licensed businesses must provide a complaints procedure and must tell you how to escalate to the named alternative dispute resolution provider if the complaint is unresolved.
The degradation pattern is recognisable: live chat is responsive about deposits and evasive about payouts; a complaint acknowledged and then not progressed; a final response promised and not delivered; the escalation route unnamed when asked for.
That last item is the one to test early, because it costs nothing. Ask support, in writing, to name the ADR provider and the deadline for a final response. Keep the answer. If the answer never comes, you have already established the gap you would be relying on later.
At the point where the internal process has stalled, the practical step is to refer the complaint rather than continue arguing. A referral is not an escalation of tone; it is a change of forum, and it works better with records than with indignation.
Signals before you deposit
Some warning signs are visible without an account. No company name in the terms. No named ADR provider. A licence badge that is an unlinked image. Withdrawal terms that cannot be found as a separate section. A bonus whose headline is prominent and whose conditions are not published on the same page.
Others appear in the first minutes of using the cashier. Deposit limits stated and withdrawal limits absent. Verification deferred with a message saying documents may be requested later. A minimum withdrawal that is high relative to the minimum deposit.
None of these proves anything by itself. Two or three together are enough to choose differently while the choice is still free, which is the entire argument for doing the reading before the deposit rather than after the win.
If you are already in a dispute, the same list tells you what to collect. Every item above is a document, a screenshot or a date — which is to say, evidence.
- Collect the dates: requests, uploads, quoted timescales, elapsed periods.
- Compare every cited clause with your saved version of the terms.
- Ask in writing for the specific outstanding items and the specific reason for the hold.
- Ask in writing for the named ADR provider and the final-response deadline.
- Refer the complaint once the internal process has stalled, with the record attached.
What not to do
Do not open a second account to work around a restriction. Duplicate accounts are a breach of most terms and hand the operator a clean reason to void a balance that was otherwise arguable. Do not send unredacted identity documents to an email address you were given in chat without confirming it through the site itself.
Do not keep depositing to maintain access while a payout is held; that turns a dispute about one balance into a pattern of losses. And do not treat recovery of a held balance as a reason to continue gambling. If the dispute is causing distress, the help routes on this site are independent of the operator and do not require the dispute to be resolved first.
FAQ
Is a document request a bad sign?
No. Licensed operators must verify identity and may ask about source of funds. The signal is a request that arrives only after a win, repeats without a stated defect, and never produces a shortening list.
How long should a withdrawal review take?
There is no single lawful figure, which is why the operator’s own published timescale matters. Record each quoted period and whether it was met; an unmet, unexplained period is the measurable part of a complaint.
The casino says my play was irregular. Can it void the balance?
It depends on the clause and whether it was clearly presented. Ask for the definition being applied and the specific bets relied on, and compare the clause with the version you saved.
Should I threaten a chargeback?
A chargeback is a payment dispute, not a gambling dispute, and it can close the account and complicate the complaint. The ADR route is the one designed for this and should normally come first.
What if the operator simply stops replying?
Note the date the final-response deadline passed and refer the complaint to the named ADR provider with your record. Silence does not pause the route; it opens it.
Next pages
Sources and scope
- UK Gambling Commission: age and identity verification, checked 18 November 2026.
- UK Gambling Commission: taking a complaint to an ADR provider, checked 18 November 2026.
- UK Gambling Commission: Licence Conditions and Codes of Practice, checked 18 November 2026.
Checked 18 November 2026. Regulatory claims apply to Great Britain (England, Scotland and Wales) unless a source states a wider scope. Product availability must be rechecked in the live cashier.